Note: Original SEO article synthesized from current U.S. inflation, consumer payment, and Gen Z financial behavior research; no source links included per request.
For a generation raised on tap-to-pay, one-click checkout, Venmo requests, digital wallets, and banking apps that look friendlier than most family group chats, Gen Z’s sudden affection for paper money may seem surprising. Yet here we are: young adults are pulling cash from ATMs, dividing bills into envelopes, and using physical dollars to fight back against a cost of living that keeps sneaking up like a subscription nobody remembers signing up for.
The trend is often called “cash stuffing,” but the idea is older than TikTok, older than budgeting apps, and possibly older than that mysterious envelope of coupons in your grandmother’s kitchen drawer. The method is simple: assign cash to spending categories such as groceries, gas, coffee, dining out, entertainment, personal care, and savings. When the envelope is empty, the spending stops. No complicated spreadsheet. No app notifications. No pretending that four small purchases “do not count” because they happened before lunch.
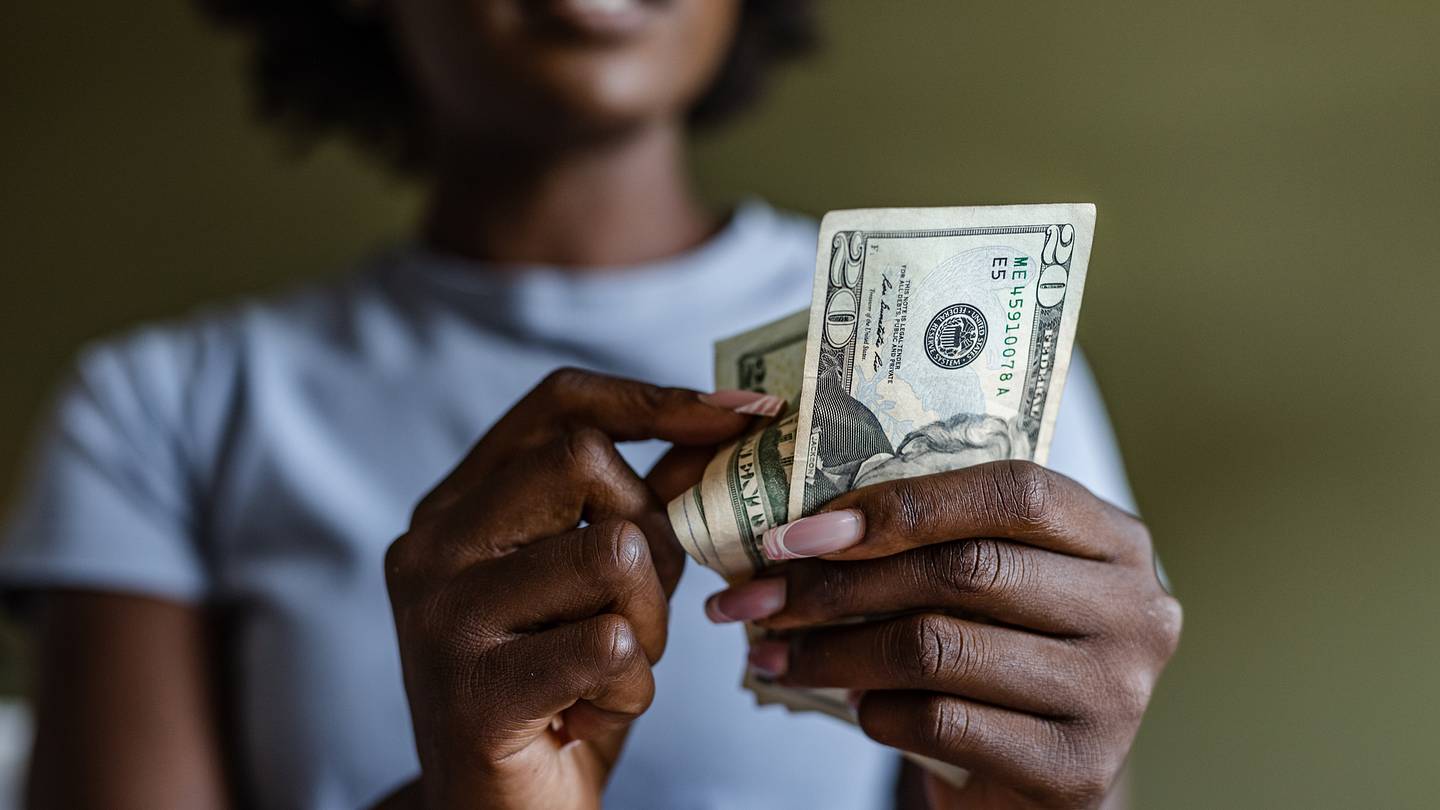
Inflation has made this old-school system feel fresh again. Even when wages rise, everyday costs can climb faster than young workers expect. Groceries, rent, utilities, transportation, insurance, and dining out now take a larger bite out of entry-level paychecks. For Gen Z, cash is becoming less of a relic and more of a financial speed bump. In a world where digital payments make spending feel almost invisible, cash makes money visible, touchable, and finite.
Why Gen Z Is Reconsidering Cash in an Inflationary Economy
Gen Z entered adulthood during a strange economic chapter. Many were students or new workers during the pandemic. Then came elevated inflation, higher interest rates, expensive housing, rising grocery bills, and a job market that can feel both full of opportunity and weirdly unstable. In theory, young adults have more financial tools than any generation before them. In practice, those tools do not make eggs, rent, or car insurance cheaper.
Recent U.S. inflation data shows why budgets feel tight. Consumer prices have continued to rise across essentials, including food, energy, shelter, and services. For a young adult building a life from scratch, a few percentage points of inflation are not abstract. They show up as a smaller grocery haul, a postponed dentist appointment, a skipped dinner out, or a credit card balance that refuses to behave.
Gen Z is responding with a mix of realism and creativity. Many young adults are cutting back on dining out, shopping at lower-cost grocery stores, paying down debt, building emergency savings, and talking more openly about money with friends. That openness matters. Unlike older generations that often treated personal finance as a secret locked in a drawer, Gen Z has made budgeting social. They post savings challenges, share debt payoff updates, normalize thrift shopping, and announce “I’m not going because I’m saving money” with the confidence of someone declining a suspicious group project.
What Is Cash Stuffing?
Cash stuffing is a budgeting method where people divide physical money into envelopes, binders, wallets, or labeled pouches for specific spending categories. It is also known as the cash envelope system. A person might have one envelope for groceries, one for gas, one for fun money, one for gifts, one for beauty or grooming, and another for savings goals.
The system usually starts with a paycheck. After fixed expenses are handled, the remaining flexible spending money is split into categories. For example, a Gen Z worker taking home $2,800 a month might pay rent, utilities, insurance, and student loans digitally. Then they may withdraw $450 in cash for groceries, $120 for gas, $100 for restaurants, $80 for coffee and snacks, $75 for personal care, and $100 for weekend fun. Once the restaurant envelope is empty, the message is beautifully blunt: the kitchen is now open.
Why Cash Feels Different From Cards
Cash changes the psychology of spending. A card tap is fast, clean, and almost emotionally weightless. A twenty-dollar bill leaving your hand feels more dramatic. It is not exactly Shakespeare, but the plot is clear: money was here, and now it is not.
Behavioral finance research has long explored the “pain of paying,” the idea that people feel the cost of a purchase more strongly when payment is tangible and immediate. Credit cards, digital wallets, and buy now, pay later services can reduce that feeling. They separate the pleasure of buying from the discomfort of paying. Cash reconnects the two. For impulse categories, that friction can be useful.
This is why cash stuffing appeals to young adults who are tired of checking their bank account and wondering how “just a few small things” became a financial crime scene. Cash creates a hard boundary. You can see the money shrinking. You can count what remains. You can decide, in real time, whether the $9 smoothie is truly a personality requirement.
Inflation Has Turned Budgeting Into a Survival Skill
Budgeting used to be framed as something people did to become rich. Today, many Gen Z adults treat budgeting as something they do to stay steady. Inflation has shifted the goal from “How do I optimize every dollar?” to “How do I make sure this paycheck survives until the next one?”
The pressure is especially visible in categories that cannot easily be avoided. Rent is due whether or not someone had a financially inspiring morning. Groceries are necessary, even when cereal suddenly costs like it attended private school. Transportation, utilities, phone bills, and insurance keep arriving with the confidence of bills that know they are nonnegotiable.
Cash helps Gen Z isolate the parts of the budget they can control. They may not be able to negotiate rent every month, but they can set a restaurant limit. They may not control gas prices, but they can plan errands more carefully. They may not stop inflation, but they can stop a week of “small treats” from turning into a balance they regret.
Why Digital Natives Are Choosing an Analog Tool
Gen Z is not rejecting technology. They are using cash because technology has made spending too easy. The same phone that tracks a budget also delivers food, advertises flash sales, stores cards, recommends products, and allows purchases in seconds. Convenience is wonderful until it becomes a trapdoor.
Digital payments are excellent for bills, security, rewards, and records. But for flexible spending, they can blur the line between planned purchases and emotional purchases. Cash restores that line. It turns spending from a background activity into an intentional decision.
There is also a cultural side. Social media has made budgeting visual. Cash binders, labeled envelopes, pastel trackers, savings challenges, and “reset day” videos turn personal finance into a routine people can watch and copy. Some critics dismiss this as performative, but the visibility can be helpful. A budget that feels boring often gets ignored. A budget that feels organized, aesthetic, and emotionally rewarding has a better chance of surviving real life.
The Benefits of Using Cash to Control Spending
1. Cash Makes Limits Obvious
A digital budget can show a number, but cash shows a limit. When the grocery envelope has $40 left, there is no mystery. The shopper must choose carefully. That simple visibility can prevent overspending before it happens.
2. Cash Reduces Impulse Purchases
Impulse spending thrives on speed. Cash slows the process down. Counting bills, breaking a larger note, and seeing what remains can create just enough pause to reconsider a purchase. That pause is powerful, especially for categories like coffee, takeout, clothes, cosmetics, and convenience-store snacks.
3. Cash Can Help Avoid Credit Card Debt
Credit cards can be useful when paid in full, but they become expensive when balances carry over. For young adults dealing with high interest rates and tight cash flow, using physical money for discretionary spending can reduce the temptation to swipe first and panic later.
4. Cash Encourages Weekly Planning
Cash stuffing works best when paired with regular check-ins. Many Gen Z budgeters review their envelopes weekly, move leftover cash into savings, and adjust categories based on real spending. This creates a feedback loop. Instead of discovering a budget problem at the end of the month, they notice it while there is still time to fix it.
5. Cash Makes Saving Feel Tangible
Digital savings accounts are efficient, but watching a savings envelope grow can be motivating. Whether the goal is an emergency fund, a trip, a laptop, holiday gifts, or a security deposit, physical progress can turn saving from a vague good intention into a visible win.
The Downsides: Cash Is Helpful, Not Magical
Cash budgeting is not perfect. It can be lost or stolen. It does not offer the same fraud protections as credit cards. It does not build credit history. It is inconvenient for online bills, subscriptions, travel bookings, and many modern services. Carrying too much cash can also create safety concerns.
There is another risk: false flexibility. Some people may treat cash as “already spent” once withdrawn, which can encourage careless purchases. Others may forget to track where the cash went. A wallet full of bills is not a plan by itself; it is only a tool. Without realistic categories and regular reviews, cash can disappear just as quickly as digital money, only with fewer receipts.
The best approach is usually hybrid. Use digital payments for fixed bills, automated savings, retirement contributions, and secure transactions. Use cash for spending categories that tend to leak money. For many Gen Z adults, that means groceries, takeout, coffee, entertainment, beauty, clothing, and weekend plans.
How to Start a Gen Z-Friendly Cash Budget
Starting with cash does not require a dramatic financial makeover. No one needs to buy a glitter binder, alphabetized envelopes, or a label maker powerful enough to organize the Pentagon. A basic system works fine.
Step 1: Track One Month of Spending
Before creating cash categories, review actual spending. Look at bank statements and card transactions. Identify where money leaks. Common categories include food delivery, coffee, snacks, rideshare trips, clothes, convenience shopping, and social plans.
Step 2: Choose Three to Six Cash Categories
Do not stuff cash for every expense. Rent, utilities, loan payments, subscriptions, insurance, and phone bills usually work better digitally. Cash is most useful for flexible spending. Start with categories that cause the most budget stress.
Step 3: Set Realistic Limits
A budget that is too strict will collapse faster than a cheap umbrella in a thunderstorm. If someone usually spends $400 a month eating out, setting the envelope at $40 may feel heroic for three days and impossible by Friday. A better goal may be reducing the category gradually.
Step 4: Review Weekly
Pick a reset day. Count what remains, move leftover cash to savings or debt payoff, and adjust the next week. Weekly reviews make the system flexible without becoming chaotic.
Step 5: Keep Safety in Mind
Store cash securely. Avoid carrying every envelope at once. Use a debit or credit card for travel, large purchases, and situations where fraud protection matters. Cash is a budgeting tool, not a dare.
What the Cash Trend Says About Gen Z
The return to cash says less about nostalgia and more about control. Gen Z is often stereotyped as financially careless, but their behavior tells a more complicated story. Many young adults are trying to save earlier, avoid debt, negotiate spending boundaries, and talk honestly about affordability. They may still buy small treats, subscribe to streaming platforms, or splurge on self-care, but they are also questioning old assumptions about success.
For Gen Z, financial wellness is not only about owning a house someday or retiring at 65. It is also about feeling less anxious this week. Cash budgeting fits that emotional need. It provides a small zone of control in an economy that can feel unpredictable.
There is also a quiet rebellion in the trend. A generation surrounded by financial technology is saying that more convenience is not always better. Sometimes the smartest tool is the one that makes you pause. Sometimes the “upgrade” is an envelope.
What Brands and Businesses Should Learn
Businesses targeting Gen Z should pay attention. This generation is value-conscious, skeptical of vague pricing, and quick to compare options. They appreciate transparency, discounts that actually matter, flexible payment options, and brands that respect tight budgets.
Inflation has made young consumers more selective. They may trade down on basics, use coupons, buy secondhand, split costs with friends, or choose experiences carefully. A brand that assumes Gen Z will buy anything because it looks good online may be in for a humbling meeting with reality.
Clear prices, honest value, loyalty rewards, smaller affordable options, and no-surprise fees can make a difference. Gen Z does not necessarily want the cheapest product every time. They want to know why something is worth the money. In an inflationary economy, “because it is trending” is not always enough.
Experiences: How Gen Z Is Using Cash to Fight Everyday Inflation
Imagine a 24-year-old marketing assistant named Maya. She gets paid every other Friday, and by Monday morning she used to feel financially optimistic. By the following Thursday, optimism had left the chat. Her bank app showed a trail of small purchases: $7 coffee, $18 lunch, $12 drugstore run, $32 rideshare, $46 takeout, $9 snack, $21 online sale. None of the purchases looked irresponsible alone. Together, they were the budget equivalent of death by a thousand convenience fees.
Maya started withdrawing $180 every payday for food outside the home, coffee, and weekend fun. She split it into three envelopes. The first week felt awkward. Paying cash for coffee made her feel like she had accidentally time-traveled to 2008. But by the second week, she noticed something useful: she was not depriving herself; she was choosing. If she wanted brunch on Saturday, she skipped two weekday coffees. If she wanted takeout after work, she packed lunch the next day. Cash turned vague guilt into clear trade-offs.
Then there is Jordan, a 22-year-old student working part-time while finishing school. His biggest inflation shock was groceries. He used to walk into the store with a debit card and a dream. The dream usually included snacks, frozen meals, energy drinks, and at least one item purchased because the packaging looked emotionally supportive. He began bringing $75 in cash for weekly groceries. At first, he had to put items back. Nobody enjoys returning fancy granola to the shelf like it personally betrayed them. But the habit helped him compare unit prices, plan meals, and stop treating the grocery store like a treasure hunt.
For Alina, 27, cash helped with social spending. Her friends loved concerts, restaurants, birthday dinners, weekend markets, and last-minute plans. She wanted to join, but every invitation came with an invisible price tag. Instead of disappearing or making excuses, she started “loud budgeting.” She told friends she had $120 a month for going out and would happily join plans that fit. To her surprise, several friends admitted they were stressed too. The group started mixing expensive nights with low-cost hangouts: potluck dinners, free museum days, walks, movie nights at home, and coffee instead of full meals. Cash did not just change her wallet; it changed the conversation.
Another common experience is the subscription audit. Many Gen Z adults are not overspending because they buy luxury items every week. They are overspending because money quietly leaks through apps, memberships, cloud storage, streaming platforms, delivery fees, and premium versions of services they barely use. Cash stuffing often reveals this because the flexible spending envelope feels too small. When that happens, the problem may not be the envelope. The problem may be the silent digital charges draining the account before the month begins.
One practical approach is the “cash plus calendar” method. Fixed digital bills go on a calendar. Flexible categories go into cash envelopes. Savings transfers happen automatically on payday. A weekly reset keeps the system honest. This hybrid method gives Gen Z the best of both worlds: the security and convenience of digital finance, plus the awareness and discipline of physical money.
Cash also changes emotional spending. A young worker having a bad day may still want a treat, and that is not a moral failure. The difference is that cash creates a container. A $25 self-care envelope can fund a latte, a face mask, a used book, or a small dessert. When the envelope is empty, the answer is not “you are bad with money.” The answer is simply “not this week.” That gentler boundary can reduce shame, which is important because shame rarely builds good habits. It usually just makes people avoid looking at the numbers.
The most successful Gen Z cash users are not trying to live like monks with Wi-Fi. They are trying to create breathing room. They still use phones, apps, cards, online banking, and automatic transfers. They still enjoy convenience. But they have learned that when inflation squeezes the budget, visibility matters. Cash shows what is left. It makes overspending harder to ignore. And sometimes, the simple act of counting bills before a purchase is enough to ask the most powerful budgeting question: “Do I really want this, or am I just tired?”
Conclusion
Gen Z turning to cash is not a rejection of modern finance. It is a response to modern pressure. Inflation, high living costs, debt concerns, and digital spending fatigue have pushed many young adults to look for tools that make money feel real again. Cash stuffing and envelope budgeting work because they are simple, visual, and immediate. They help people slow down, set limits, and make trade-offs before the bank account gets dramatic.
The trend will not solve inflation by itself. Cash cannot lower rent, reduce grocery prices, or make student loans vanish in a puff of financial glitter. But it can help young adults regain a sense of control. In a world of invisible payments and rising prices, that control is valuable. Sometimes the smartest financial technology is not an app. Sometimes it is a labeled envelope and the courage to stop spending when it is empty.