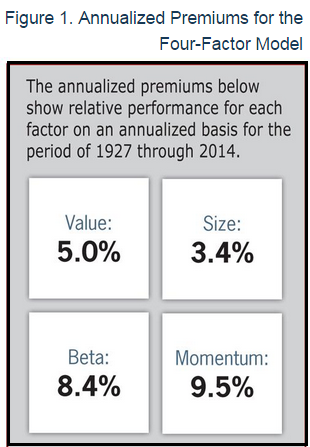
Momentum investing sounds almost too simple to be respectable: buy what has been winning, avoid what has been losing, and try not to trip over your own shoelaces on the way out. Yet for decades, researchers, asset managers, and market veterans have kept coming back to the same uncomfortable conclusion: momentum is real. Not perfect, not permanent, not magical, but real.
That matters because momentum investing sits at the intersection of market behavior, investor psychology, and cold-blooded portfolio rules. It is one of those rare ideas that feels suspiciously obvious once you hear it, which is exactly why many people dismiss it too quickly. But markets do not move only because spreadsheets say they should. They move because information spreads unevenly, institutions react slowly, and investors have a well-documented habit of chasing what already looks successful. In other words, markets are populated by humans, committees, algorithms trained by humans, and the occasional person who buys a stock because their cousin’s barber “has a good feeling.”
This is why momentum investing works often enough to deserve serious attention. It captures the tendency for winners to keep winning for a while and for losers to keep losing for a while. The keyword is for a while. Momentum is not a forever strategy. It is a medium-term pattern, and the investors who understand that distinction are the ones most likely to use it well.
What Momentum Investing Actually Is
At its core, momentum investing means favoring securities that have recently outperformed and avoiding, underweighting, or shorting securities that have recently lagged. In plain English, it says price strength can persist. A stock, sector, or asset class that has been climbing may continue climbing long enough for disciplined investors to benefit. Meanwhile, the stuff falling down the stairs may keep bouncing in the wrong direction.
In many systematic strategies, momentum is measured by looking at returns over the past 6 to 12 months, often excluding the most recent month. That “skip a month” approach is designed to reduce noise from very short-term reversals. The strategy can be applied to individual stocks, industries, countries, exchange-traded funds, or even other asset classes like bonds and commodities.
Importantly, momentum is not the same thing as randomly buying hot stocks on a Tuesday afternoon because social media is yelling in all caps. True momentum investing is rule-based. It relies on rankings, rebalancing, diversification, and risk controls. Done properly, it is closer to a disciplined system than a hype-fueled guessing game.
Why Momentum Investing Works: The Four Big Reasons
1. Markets do not absorb information all at once
The first reason momentum works is that markets are not as instantly efficient as finance textbooks once liked to imagine. New information does not always slam into prices like a lightning bolt. Quite often, it drips in. Earnings surprises, guidance changes, business improvements, product wins, and macro shifts can take time to be fully understood and priced.
That slow adjustment creates a window where price trends continue. A company reports improving margins, analysts revise estimates upward, investors gradually gain confidence, and the stock keeps moving higher. The initial jump may be only the opening act. Momentum investors try to catch the rest of the performance rather than insisting they were owed front-row seats at the exact first minute.
This slow diffusion of information is especially relevant when news is complicated, when analyst coverage is limited, or when investors are distracted by bigger market stories. Sometimes the market knows something good happened, but it takes a while to appreciate how good it really was. Momentum lives in that gap.
2. Investors underreact first, then overreact later
This is the behavioral-finance plot twist that makes momentum especially interesting. In the early phase, investors often underreact to new information. They are cautious, anchored to older views, or simply late to update their beliefs. That helps trends persist.
Later, however, the opposite can happen. Once a trend becomes obvious, investors pile in. Fund managers do not want to look foolish for missing the winners. Retail investors experience the classic fear of missing out. Financial media starts writing dramatic headlines. Suddenly, what began as a rational repricing becomes a crowd event.
That combination helps explain why momentum can work in the medium term and then reverse over the long term. Early underreaction gets the trend started. Later return-chasing stretches it. Eventually prices can run ahead of fundamentals, and the whole thing snaps back with the elegance of a rubber band to the face.
3. Institutions move more slowly than people think
Many investors imagine giant institutions as omniscient market machines. In reality, institutional investing often involves committees, mandates, risk limits, benchmark constraints, client expectations, and internal politics. Even when a manager recognizes a trend, acting on it may take time.
A pension plan cannot necessarily overhaul its holdings overnight. A mutual fund manager may be reluctant to deviate too far from a benchmark. A large asset manager has to think about liquidity and market impact. Research teams need confirmation. Compliance teams need documentation. Someone schedules a meeting. Another person schedules a meeting about the meeting. By then, the trend may already have another month of life in it.
This institutional friction helps momentum persist. Price moves are not just about what is true; they are also about how quickly capital can respond to what is true.
4. Money flows tend to reinforce trends
Momentum also works because flows can feed price action. Rising stocks attract attention. Attention attracts inflows. Inflows can push prices higher, which attracts more attention, and around we go again. The loop is not infinite, but it can be powerful.
You see this in sectors, themes, and factors. A strong area of the market starts outperforming, allocators increase exposure, more managers feel pressure to own it, and trend followers add weight. None of this means the asset is automatically cheap or wise to own forever. It means trends can become self-reinforcing before they become exhausted.
That feedback loop is one reason momentum works better than many skeptics expect. The market is not only reflecting information; it is also reflecting behavior. And behavior has a habit of echoing.
Momentum Is a Pattern, Not a Superpower
All of that said, momentum investing is not some cheat code hidden under the market’s keyboard. It works because it captures a persistent tendency, not because it predicts the future with mystical certainty. The future still reserves the right to be rude.
Momentum tends to work best in environments where leadership persists. It tends to struggle when leadership changes violently. Sharp rebounds after market selloffs can be particularly painful. Why? Because yesterday’s losers can suddenly become tomorrow’s rockets, and a momentum strategy may be positioned the wrong way around when the reversal hits.
This is why serious momentum investors obsess over risk management. They diversify. They use broad baskets rather than single-stock heroics. They manage turnover. They think about volatility. They accept that momentum can look brilliant for a while and then spend a season looking like it misplaced its glasses.
Why Implementation Matters So Much
One of the biggest mistakes beginners make is assuming that because the momentum premium exists in research, every momentum product or DIY momentum portfolio will automatically capture it. Not even close.
Momentum can be expensive to trade. High turnover creates transaction costs, tax drag, and market impact. A paper portfolio can rebalance cleanly on a spreadsheet. Real money has to deal with bid-ask spreads, liquidity, and the annoying reality that other people are trading too.
That is why implementation is everything. Some managers use momentum signals mainly to improve trading decisions rather than to build a pure, high-turnover momentum portfolio. Others combine momentum with factors such as quality or value to reduce the risk of owning the market’s most speculative darlings at the exact wrong moment. The best momentum approaches are usually less flashy than people expect. They are systematic, diversified, and humble about costs.
In other words, momentum works better when it is treated like portfolio engineering and worse when it is treated like a casino field trip.
When Momentum Investing Shines
Persistent earnings improvement
When companies keep posting stronger results and analysts keep lifting expectations, momentum can thrive. Good fundamentals and rising prices often make excellent dance partners.
Clear sector leadership
When one part of the market leads for months rather than days, momentum has a cleaner runway. Trends in technology, industrials, healthcare, or energy can persist longer than impatient investors expect.
Broad market confidence
Momentum often does well when investor sentiment is constructive and leadership is stable. The strategy likes follow-through more than chaos.
When Momentum Investing Struggles
Violent market reversals
Momentum can get crushed when beaten-down names suddenly rebound hard and leadership flips. This is the classic momentum crash scenario.
High volatility and whipsaw markets
When the market changes direction every other week, momentum has trouble latching onto anything durable. It is hard to ride a trend that keeps changing costumes mid-scene.
High costs and sloppy execution
Even a sound idea can be ruined by excessive turnover, poor liquidity, concentrated bets, and taxes. Momentum does not forgive operational laziness.
Common Myths About Momentum Investing
“It is just performance chasing.”
Bad momentum investing is performance chasing. Good momentum investing is systematic exposure to a well-documented return pattern. One is emotional. The other is rules-based.
“It only works in bull markets.”
Not exactly. Momentum can work in different environments and across multiple asset classes, though the ride is rarely smooth. What it needs most is trend persistence, not blind optimism.
“It is the opposite of fundamentals.”
Also false. Momentum often works best when paired with fundamental strength. A company with improving earnings and rising relative strength can be much more attractive than a stock that is merely fashionable for five loud minutes.
“It is easy.”
Conceptually, yes. Emotionally, absolutely not. Momentum requires buying things that already look expensive to bargain hunters and selling things that look “cheap” to hopeful optimists. Humans are not naturally wired for that. We love stories, bargains, and heroic turnarounds. Momentum often says, “That is adorable, but the trend is still down.”
The Bottom Line
Momentum investing works because markets are made of people, and people are gloriously imperfect. Information travels gradually. Investors anchor to old beliefs. Institutions move slowly. Crowds chase what is already working. Trends feed on themselves for a while. All of that creates return persistence that disciplined investors can try to capture.
But the same forces that make momentum powerful also make it dangerous when used carelessly. Trends can reverse. Costs can eat returns. Emotion can wreck discipline. That is why momentum is best understood not as a magic formula, but as a recurring market pattern that rewards structure, patience, diversification, and respect for risk.
If value investing is the art of buying what looks too cheap, momentum investing is the art of admitting the market may know something before your pride does. And honestly, that may be its most profitable lesson.
Experiences Related to Why Momentum Investing Works
Experience 1: The investor who stopped trying to be the smartest person in the room. One common experience among momentum-minded investors is the realization that being early is not the same as being right. A lot of people begin their investing life hunting for “undervalued” stocks that stay undervalued for what feels like several geological eras. Then they notice something annoying: the stocks making money are often the ones already moving higher. That does not mean fundamentals do not matter. It means price strength can contain useful information. Investors who make this shift often describe momentum as the moment they stopped arguing with the tape and started listening to it.
Experience 2: The trend that looked too expensive and kept going anyway. Another familiar experience is seeing a stock, sector, or ETF rise sharply, assuming it must be “overdone,” avoiding it, and then watching it continue climbing for months. That is momentum in real life. The market rarely sends a handwritten note announcing that a new leader has officially arrived. Instead, leadership emerges gradually. What looks expensive on day one can look obvious by month six. Momentum investors learn to accept that a stock can be up a lot and still have room to run, especially when earnings revisions, fund flows, and sentiment are all moving in the same direction.
Experience 3: The painful reversal that teaches risk control. On the flip side, almost every serious momentum investor has a battle scar from a sharp reversal. A strategy that looked brilliant in a smooth trend can get knocked sideways when the market suddenly rotates. Yesterday’s laggards become today’s comeback stories, and the portfolio feels like it brought last season’s wardrobe to a new season’s party. That experience usually teaches an important lesson: momentum needs diversification, position sizing, and humility. The idea works, but it does not work every week, and anyone who treats it like a guaranteed money printer usually ends up receiving a very expensive education.
Experience 4: The quiet power of rules. Perhaps the most underrated experience in momentum investing is how boring it becomes when done well. And that is a compliment. Good momentum investors often stop making dramatic predictions. They rebalance on schedule. They follow rankings. They trim what weakens and hold what stays strong. They accept that the strategy’s edge does not come from sounding brilliant at dinner parties. It comes from repeatedly doing small, disciplined things while other investors bounce between fear, greed, headlines, and hunches. Over time, that consistency is often the real secret sauce.