When the Federal Reserve makes an emergency rate cut, Wall Street does not simply read the press release, adjust a spreadsheet, and calmly return to sipping coffee. No, markets tend to react like a raccoon trapped in a pantry: noisy, emotional, and absolutely convinced something dramatic is happening. That reaction is what economists often call animal spiritsthe cocktail of fear, hope, confidence, panic, greed, and “what on earth is the Fed seeing that I’m not?” that drives financial decisions when the future looks foggy.
The phrase “Animal Spirits: The Emergency Rate Cut” captures a powerful moment in economic life. An emergency rate cut is not routine monetary housekeeping. It is the central bank equivalent of turning on the hazard lights. It tells investors, businesses, consumers, and lenders that policymakers see a serious risk to the economy and want to move quickly before fear hardens into recession.
But here is the twist: a rate cut designed to calm markets can sometimes make people more nervous. If the Federal Reserve cuts interest rates at a regularly scheduled meeting, investors may see it as normal policy. If the Fed cuts between meetings, the question becomes: “What do they know?” And suddenly, the emotional horses are out of the barn, wearing tiny trading jackets.
What Is an Emergency Rate Cut?
An emergency rate cut is an unscheduled reduction in the Federal Reserve’s target range for the federal funds rate. The federal funds rate is the short-term interest rate banks charge each other for overnight lending, but its influence spreads far beyond the banking system. It affects credit cards, auto loans, mortgages, business loans, bond yields, stock valuations, and the general price of money in the economy.
Normally, the Federal Open Market Committee, or FOMC, changes rates during scheduled meetings. Emergency cuts are different. They happen when policymakers believe waiting could worsen financial stress. The goal is to lower borrowing costs, support liquidity, encourage lending, and signal that the central bank is ready to defend the economy from a shock.
Emergency cuts have appeared during major moments of stress: financial crises, market crashes, terrorist attacks, and the sudden economic freeze caused by COVID-19. They are rare because central banks know that surprise action carries psychological consequences. A surprise rate cut can be medicine, but if delivered too dramatically, it may make the patient ask why everyone in the hospital is running.
Animal Spirits: The Psychology Behind the Market Reaction
The term animal spirits is closely associated with economist John Maynard Keynes, who used it to describe the instincts and emotions that shape economic behavior. In plain English, it means people do not make financial decisions like perfectly rational robots. They act based on confidence, stories, social cues, fear of missing out, fear of losing everything, and the strange human habit of checking stock prices as if staring harder will improve them.
During stable times, animal spirits can lift the economy. Consumers spend because they feel secure. Entrepreneurs hire because they believe demand will grow. Investors buy because tomorrow looks brighter than today. Confidence becomes fuel.
During a crisis, the same emotional engine can run in reverse. Consumers delay spending. Companies freeze hiring. Banks tighten credit. Investors sell first and ask thoughtful questions sometime next quarter. The economy can slow not only because of hard data but because everyone expects everyone else to pull back.
That is why emergency rate cuts are partly mechanical and partly theatrical. The Fed is not only adjusting interest rates; it is trying to influence expectations. It wants to say, “We are here, we have tools, and the financial system will not be left alone in a thunderstorm.” Whether people believe that message depends on the mood of the moment.
The 2020 Emergency Rate Cuts: A Case Study in Panic and Policy
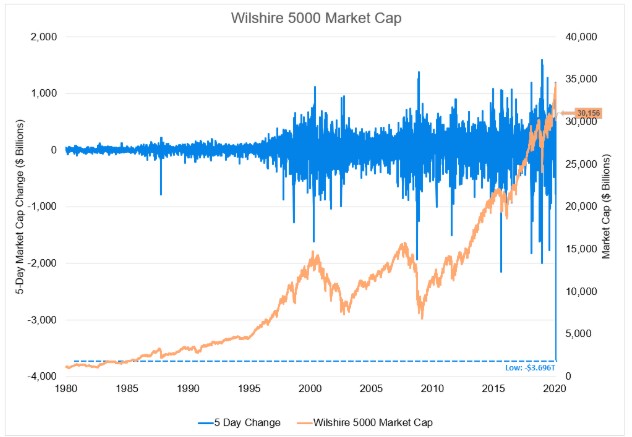
The most famous modern example came in March 2020. As COVID-19 spread, the U.S. economy faced a shock that was both medical and financial. Businesses closed, travel collapsed, supply chains jammed, and consumers retreated almost overnight. This was not a normal recession forming slowly in the distance. It was more like someone unplugged large pieces of the economy while everyone was still logged in.
On March 3, 2020, the Federal Reserve cut the target range for the federal funds rate by half a percentage point, bringing it to 1.00% to 1.25%. This was an emergency move before the next scheduled policy meeting. The intention was to support confidence and cushion the economy against coronavirus-related risks.
Markets did not respond with lasting calm. Instead, many investors interpreted the move as confirmation that the situation was worse than previously understood. The cut helped show the Fed was paying attention, but it could not reopen restaurants, repair supply chains, cure a virus, or persuade frightened households to book vacations. Monetary policy can lower the price of money; it cannot make a crowded airport feel like a brilliant idea during a pandemic.
Then, on March 15, 2020, the Fed acted again, cutting the target range to 0% to 0.25%. It also announced major purchases of Treasury securities and agency mortgage-backed securities to support market functioning. A week later, the Fed expanded its measures further, pledging to buy securities in the amounts needed to restore smoother market operations.
The speed and scale were extraordinary. The U.S. recession that began in February 2020 officially ended in April 2020, making it the shortest recession on record, but the economic damage inside those two months was violent. In April 2020, unemployment surged to 14.7%, and second-quarter real GDP later showed a historic annualized decline. The emergency rate cut was not a cure by itself. It was one part of a larger rescue effort that also included fiscal relief, lending facilities, bond purchases, and government support for households and businesses.
Why Emergency Rate Cuts Can Calm Markets
Emergency rate cuts can work when they convince investors that policymakers are ahead of the problem. Lower short-term rates reduce borrowing costs and can support asset prices by making future cash flows more attractive. Businesses may find it cheaper to refinance debt. Consumers may benefit from lower loan rates. Banks may feel more comfortable extending credit if liquidity improves.
There is also a signaling effect. When the Fed acts decisively, it tells markets that it will not ignore stress. This matters because modern finance runs on confidence. Banks lend because they believe borrowers will repay. Investors buy bonds because they believe markets will remain liquid. Companies invest because they believe customers will exist tomorrow. Confidence is invisible, but when it disappears, everyone notices.
An emergency cut can also reduce the odds of a financial panic feeding on itself. When credit markets freeze, even healthy companies can struggle to raise cash. Lower rates and central bank liquidity programs can prevent temporary stress from becoming permanent damage. Think of it as adding oil to an engine before the smoke becomes a very expensive sound.
Why Emergency Rate Cuts Can Scare Markets
Here is the uncomfortable part: emergency action can also frighten people. If a central bank acts suddenly, investors may wonder whether policymakers have seen alarming data that the public has not. The move can create a “Fed knows something” effect. Instead of thinking, “Great, help is here,” markets may think, “Why did help arrive wearing a helmet?”
Emergency cuts can also look ineffective when the crisis is not mainly caused by high interest rates. In 2020, the problem was not that consumers refused to go to concerts because credit card APRs were too high. The problem was a public-health emergency. Lower rates could support financial conditions, but they could not instantly restart normal activity.
This is where animal spirits become especially important. If fear dominates, good news may be ignored and policy support may be treated as evidence of danger. Investors may sell because others are selling. Companies may cut costs because competitors are cutting costs. Households may save more because the headlines sound scary. In that kind of environment, policy must fight both economic weakness and emotional contagion.
Emergency Rate Cuts, Stocks, Bonds, and the Dollar
Financial markets respond to emergency rate cuts in different ways. Stocks may rise if investors believe lower rates will support earnings and reduce recession risk. They may fall if investors believe the cut signals deeper trouble. Bonds often rally because lower rates make existing higher-yielding bonds more attractive, and because investors seek safety during uncertainty.
Treasury yields can fall sharply during a crisis as investors rush toward safe assets. Mortgage rates may decline too, although the relationship is not always instant or smooth. Credit spreadsthe extra yield companies pay above Treasuriescan widen if investors worry about defaults. This is why the Fed often pairs rate cuts with liquidity tools. Cutting rates is one lever; keeping markets functioning is another.
The U.S. dollar can move in either direction. Lower rates may reduce the dollar’s yield advantage, but global stress can increase demand for dollars as a safe and liquid currency. During severe crises, everyone wants cash, and often they want dollars in particular. The dollar, in these moments, becomes the financial world’s emergency flashlight.
The Difference Between a Rate Cut and a Rescue Plan
A rate cut is powerful, but it is not magic. It cannot solve every economic problem, and it works best when paired with the right supporting policies. In a banking crisis, liquidity facilities may be essential. In a household income crisis, fiscal support may matter more. In a public-health crisis, medical response and public confidence are central.
This distinction is important because investors sometimes expect the Fed to fix everything. That expectation is understandable but dangerous. The Federal Reserve can influence financial conditions, but it cannot manufacture workers, unload cargo ships, build houses overnight, or make consumers feel cheerful by waving a beige book in the air.
Emergency cuts are most effective when the problem includes tight financial conditions, frozen credit, or collapsing confidence. They are less direct when the problem is supply-driven, geopolitical, or structural. The 2020 experience showed that monetary policy can stabilize markets, but the real economy may still need targeted fiscal relief and time to heal.
What Businesses Should Learn from Emergency Rate Cuts
For businesses, an emergency rate cut is a signal to review cash, credit, and risk exposure. Lower rates may create refinancing opportunities, but they also suggest economic stress. Companies should not treat emergency cuts as a green light to borrow recklessly. They should ask practical questions: How strong is our cash position? Are customers delaying payments? Do we rely too heavily on short-term financing? Can we survive a demand shock?
Small businesses are especially vulnerable when animal spirits turn negative. Customers may spend less, banks may become cautious, and suppliers may change terms. A lower interest rate helps only if credit remains available and demand does not vanish. Smart business owners use calm periods to build flexibility so they are not forced to make desperate decisions during chaos.
Emergency rate cuts also affect pricing, hiring, inventory, and expansion plans. A company planning a new location, equipment purchase, or marketing campaign may benefit from cheaper financing. But if the cut reflects a weakening economy, management should balance opportunity with caution. Cheap money is nice. Cheap money during a storm still requires an umbrella.
What Investors Should Learn from Emergency Rate Cuts
Investors should remember that emergency cuts are not simple buy or sell signals. Context matters. A cut during a mild growth scare is different from a cut during a financial crisis. A cut that improves liquidity is different from a cut that markets interpret as panic. The same policy tool can produce very different results depending on the emotional state of investors.
Long-term investors should avoid making decisions based only on the drama of the announcement. The real questions are: Is the financial system functioning? Are earnings expectations still realistic? Are credit markets open? Is policy support broad enough? Are valuations already pricing in disaster or still pretending everything is fine?
Emergency cuts can create opportunities, but they can also create traps. Some assets rebound quickly when liquidity improves. Others remain under pressure because the underlying business damage is real. The best investors separate market plumbing problems from permanent impairment. That sounds fancy, but it means asking whether a price has fallen because people are panicking or because the business is genuinely broken.
Animal Spirits and the Fed’s Communication Challenge
Central bankers do not only manage rates; they manage language. Every word in a Fed statement is inspected like a mysterious text message from someone you just started dating. “Patient” means one thing. “Transitory” means another. “Appropriate” can move billions of dollars before lunch.
During an emergency rate cut, communication becomes even more delicate. If the Fed sounds too calm, markets may think it is behind the curve. If it sounds too worried, markets may panic. The ideal message is: “This is serious, but manageable; we are acting forcefully, but not flailing.” That is a difficult tone to strike when markets are already emotionally caffeinated.
Good communication can support animal spirits by reducing uncertainty. Bad communication can amplify fear. Investors want to know not only what the Fed is doing, but why it is doing it and what may come next. In a crisis, clarity is a policy tool.
Conclusion: Emergency Cuts Are About Money and Mood
An emergency rate cut is never just about interest rates. It is about confidence, liquidity, expectations, and the emotional weather system moving through markets. The Fed can lower borrowing costs, buy securities, and support credit flows, but the broader economy still depends on whether households, businesses, banks, and investors believe the future is stable enough to act.
That is why animal spirits matter. Markets are built from numbers, but they are moved by people. People get scared. People get greedy. People overreact, underreact, and occasionally buy airline stocks because a stranger on the internet used a rocket emoji. The emergency rate cut sits at the intersection of policy and psychology. It is both a technical move and a message to the crowd.
The lesson from 2020 and earlier crises is clear: emergency rate cuts can help stabilize the financial system, but they work best as part of a broader response. They are not magic buttons. They are confidence tools, liquidity tools, and sometimes necessary shock absorbers. When animal spirits are running wild, the central bank’s job is not merely to change the price of money. It is to convince people that the bridge ahead is still strong enough to cross.
Experiences and Practical Lessons from Emergency Rate Cut Moments
People who lived through emergency rate cut periods often remember less about the exact basis points and more about the feeling in the air. The headlines come fast. Stock prices swing wildly. Friends who never talk about bonds suddenly ask about Treasury yields. Someone at work becomes an overnight monetary policy expert after reading three posts and one very confident chart. It is a strange mix of seriousness and confusion.
For individual investors, the first experience is usually emotional whiplash. One day, lower rates sound bullish because cheaper money can support stocks. The next day, the same cut feels bearish because it suggests the economy is in trouble. This is why many investors learn the hard way that market reactions are not always logical in the short term. In a crisis, the market is not a weighing machine. It is a mood ring with leverage.
Homeowners and potential buyers may experience emergency cuts differently. They may expect mortgage rates to fall immediately, only to discover that mortgage markets have their own plumbing. Lenders price loans based on many factors, including bond yields, credit risk, servicing capacity, and demand. During stressful periods, refinancing applications can surge, lenders can become overwhelmed, and the advertised benefit of lower rates may arrive unevenly. The lesson is simple: lower Fed rates can help, but they do not guarantee instant savings for every borrower.
Business owners often feel the contradiction most sharply. On paper, lower rates reduce financing costs. In practice, emergency cuts usually arrive when customers are nervous, revenue is uncertain, and lenders may be more careful. A restaurant owner, retailer, contractor, or startup founder may not celebrate cheaper capital if sales are falling. The lived experience is less “money is cheaper” and more “how long can we keep the lights on if demand drops?” That is why emergency planning, cash reserves, and flexible expenses matter long before the Fed appears in breaking-news banners.
For employees, emergency cuts can feel distant at first. Interest rates sound like something happening in marble buildings and financial terminals. Then the real-world effects arrive: hiring freezes, delayed promotions, reduced hours, layoffs, or sudden changes in retirement account balances. Animal spirits move from Wall Street to Main Street when confidence changes behavior. A cautious CEO becomes a smaller payroll. A nervous consumer becomes lower sales. A tighter bank becomes a postponed expansion.
The most useful personal lesson is to avoid emotional decision-making during policy shocks. Emergency rate cuts are designed for unstable moments, and unstable moments are terrible environments for impulsive financial choices. Investors should revisit long-term plans instead of reacting to every market swing. Borrowers should compare actual loan terms rather than assuming all rates move together. Businesses should focus on liquidity, customer communication, and scenario planning.
Another experience worth remembering is that recovery often feels impossible before it becomes visible. During the worst moments of a crisis, pessimism can seem like intelligence. Optimism can sound naive. Yet markets and economies have repeatedly shown an ability to recover when policy support, private adaptation, and time begin working together. This does not mean every asset rebounds or every business survives. It means that fear is loudest near the point when clear thinking is most valuable.
The emergency rate cut teaches a practical truth: financial life is not only about rates, charts, and official statements. It is about behavior under uncertainty. The people who handle these periods best are rarely the ones who predict every move correctly. They are the ones who stay liquid, stay humble, check their assumptions, and refuse to let panic become a financial advisor.
Note: This article is for educational and informational purposes only. It is not financial, investment, tax, or legal advice.