America loves a good declaration. Usually it involves fireworks, a grill that’s working mostly as designed, and at least one neighbor who swears they “know what they’re doing” with a sparkler. But Declaration of Independents (the IA Magazine series) is a different kind of celebration: one that spotlights the people keeping the independent agency system alive, modern, andwhen done rightsurprisingly human.
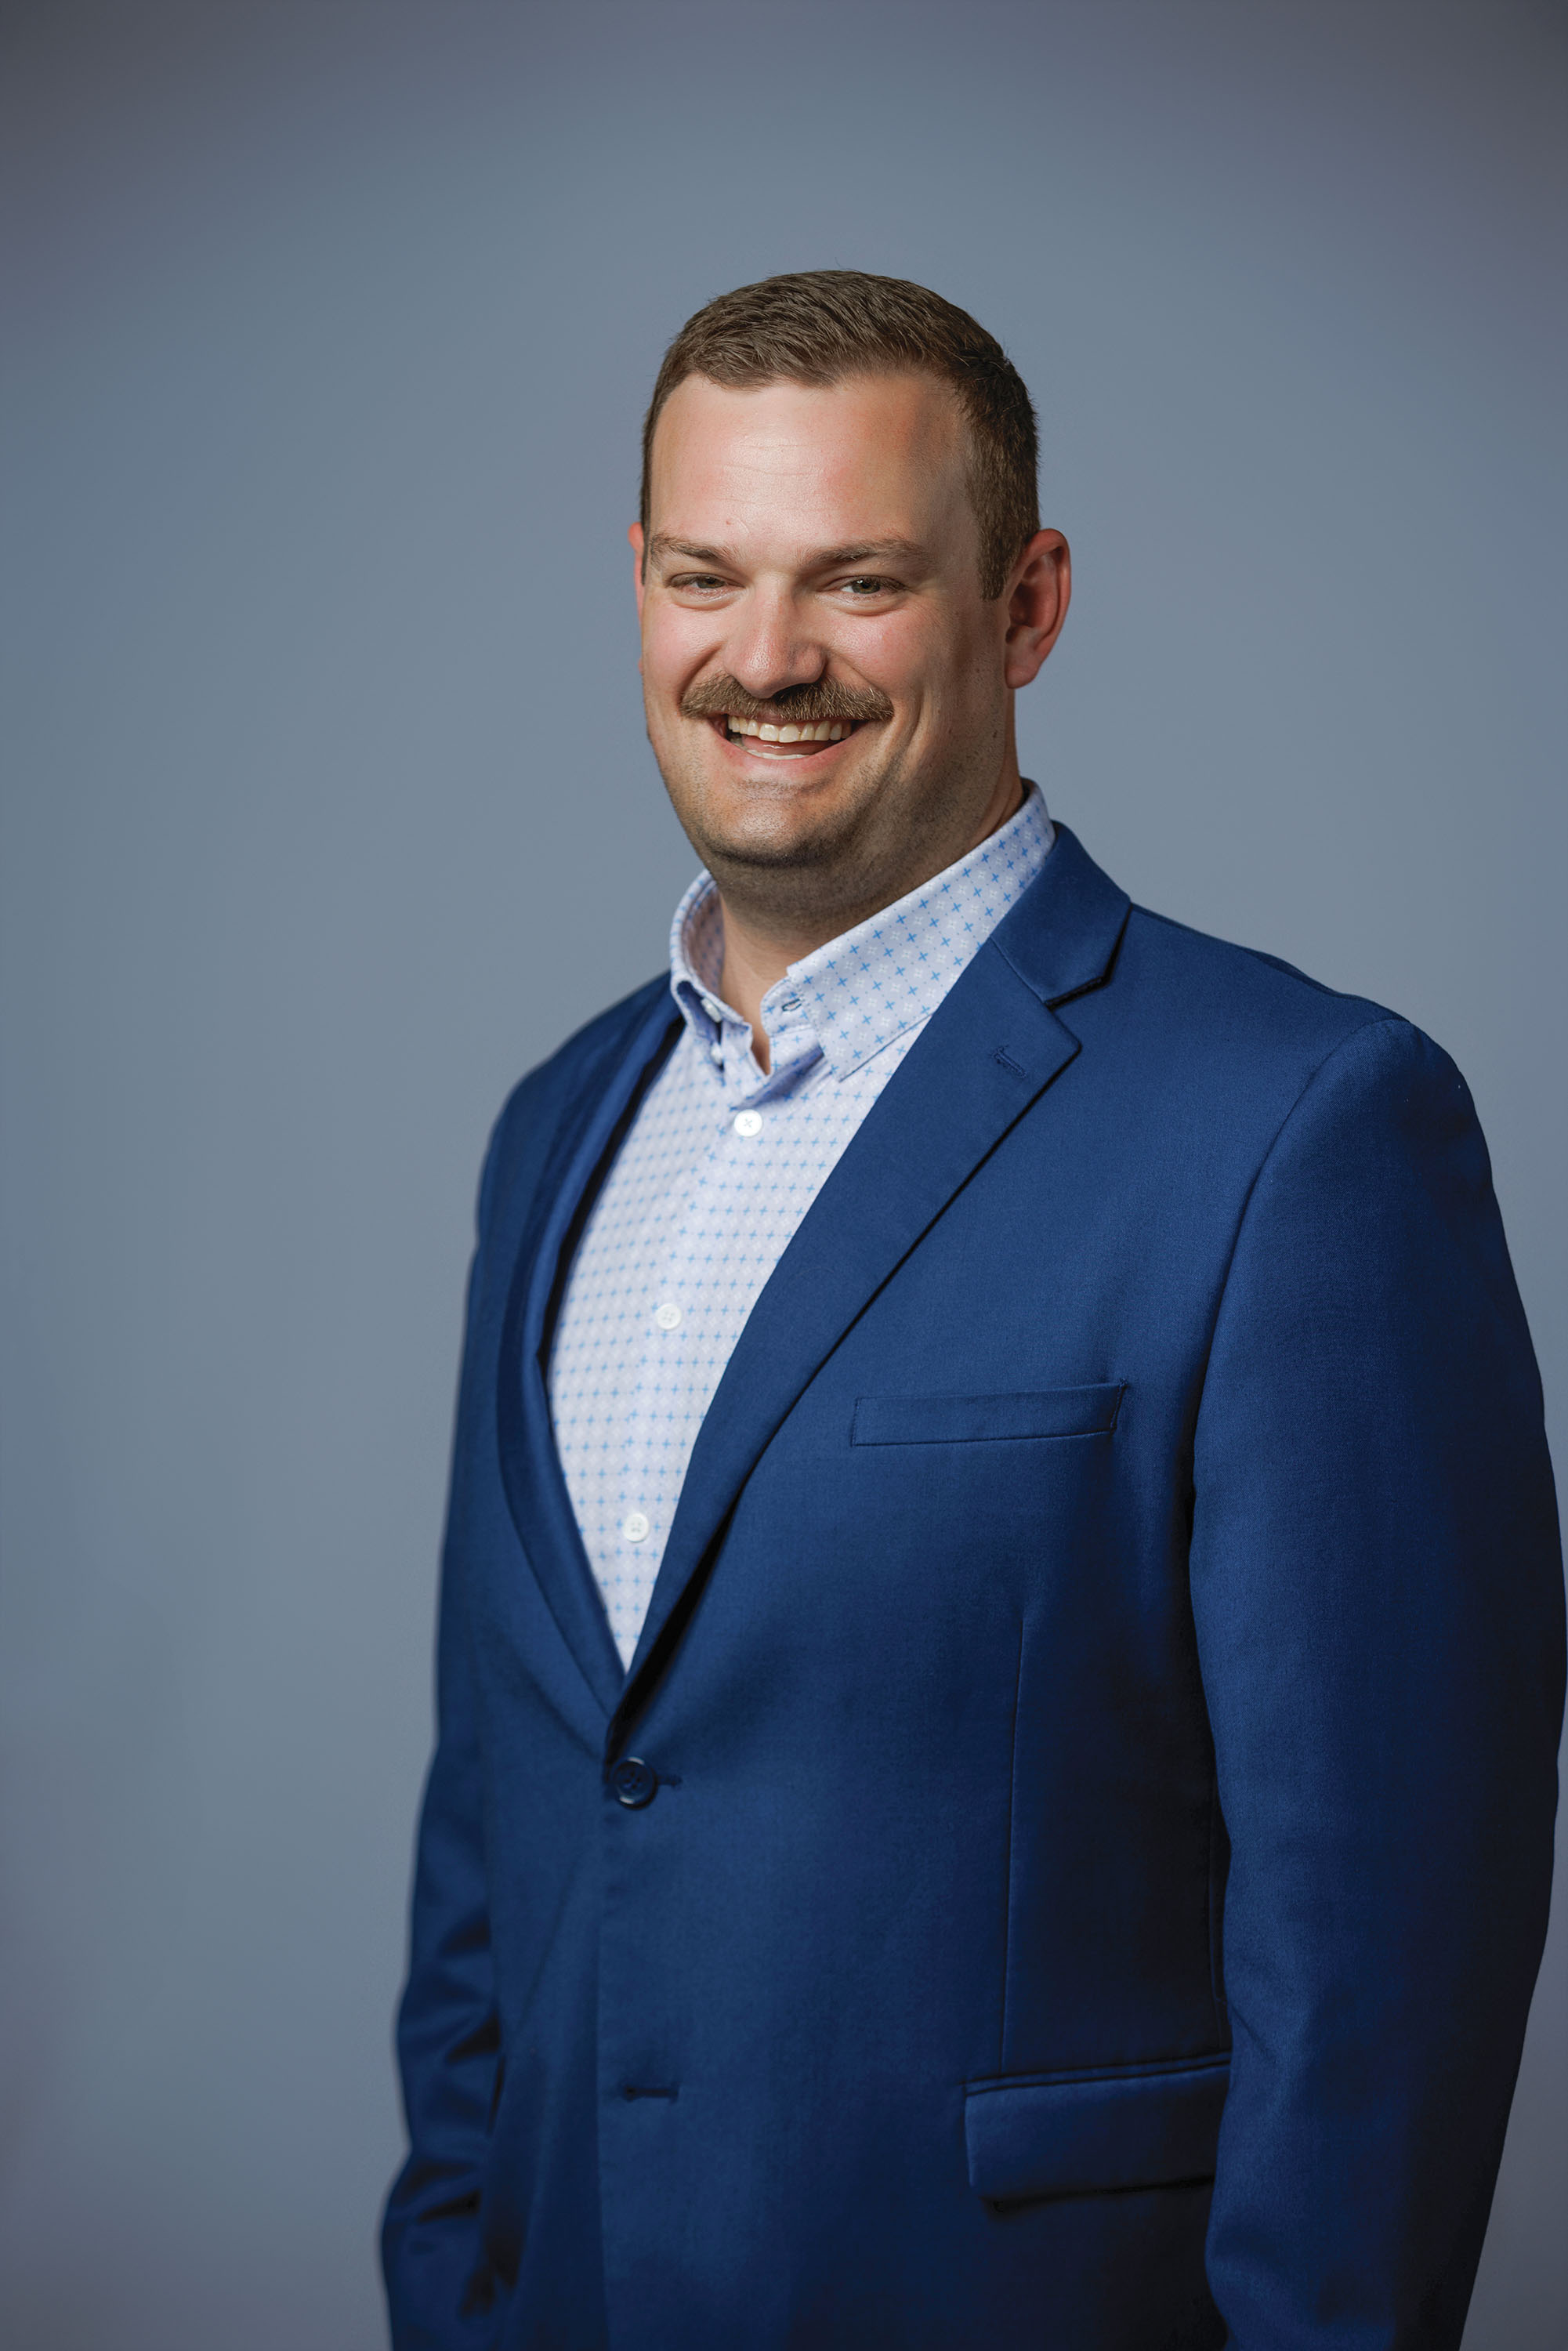
One of the most memorable profiles features Brock Elliott, a producer and partner at Elliott Insurance Group in Louisburg, Kansas. His story has everything: a third-generation family agency, a rough early start, leadership in the Big “I” Young Agents community, a deep belief in advocacy, and yesan infamous bandage-themed tattoo earned in the name of pediatric cancer fundraising. If you’re looking for a case study in what an independent insurance agent can become in 2026 (and beyond), Brock’s “declaration” is a pretty entertaining blueprint.
Why the “Declaration of Independents” Series Hits a Nerve
IA Magazine’s series works because it doesn’t treat independence like a vibe. It treats it like a job description. The independent channel is built on a simple premise: an agent isn’t tied to one carrier, so clients get options, advocacy, and (ideally) someone who can translate “policy language” into “what happens when things go sideways.” Consumers typically encounter insurance either directly through an insurer or through independent agents and brokers, and commercial insurance is commonly purchased through independent agents or brokersbecause complexity loves company.
The series also quietly argues for something bigger: independent agencies aren’t just selling protection, they’re sustaining local businesses, local nonprofits, and local communities. Which makes Brock Elliott a particularly fitting featurebecause he treats “community” like an operating system, not a slogan.
Who Is Brock Elliott (and Why IA Magazine Put Him in the Spotlight)
Third-generation roots, Kansas grit
Brock Elliott is a producer and partner at Elliott Insurance Group in Louisburg, Kansasan agency with deep family roots. His grandfather started the business in 1974, his father joined in 1984, and Brock came on board in 2012. That history matters, because the independent agency system is full of family-run firms where “succession planning” is both a business strategy and a Thanksgiving conversation.
He didn’t love insurance… until he did
Brock’s origin story isn’t the “I dreamed of premiums and endorsements as a child” variety. Like a lot of young professionals, he tried college, tried other paths, and eventually decided to give the family business a shot. Early on, he struggled. His first sales setup was brutal: get licensed, sit in a cubicle, get handed a phone book, and start calling strangers. That’s not a sales process; that’s a character-building exercise disguised as employment.
What changed wasn’t his personalityit was his seat on the bus. He moved through roles (including service and account executive work), figured out he thrives on relationships and problem-solving, then returned to sales with more confidence and better fit. The lesson is unglamorous but real: in independent agencies, “talent” often isn’t missingit’s misplaced.
Revitalizing Young Agents of Kansas: More Than “Beer and Golf”
Brock became a driving force in the Big “I” community at both state and national levels, serving as chair of the Young Agents of Kansas (YAK) and later chairing the national Young Agents Committee (YAC). When he joined YAK, the program leaned hard into social hangoutsfun, but fading. Attendance was slipping, and the energy wasn’t translating into leadership, professional development, or industry impact.
His refresh wasn’t about banning fun. It was about expanding the menu. He saw how national young agent initiatives blended networking with community service, professional growth, and political involvementand brought that mindset back home. In other words: keep the relationships, add the mission.
Why that shift matters (especially for SEO, hiring, and retention)
The insurance industry is staring down a well-documented talent challenge: an aging workforce, a pipeline problem, and a public perception that the work is mostly “emails and paperwork.” IA Magazine and major industry voices have been blunt: the narrative has to change, and the entryways have to multiply.
Brock’s YAK reboot is a practical answer. When young agents experience the industry as leadership + purpose + community, you stop competing with every other “cool job” on the internet and start offering something surprisingly rare: a stable career with real-world impact (and sometimes a tattoo you didn’t plan for).
The Bandage Tattoo: A Fundraiser That Became a Masterclass
The moment everyone remembers: a charity challenge tied to Noah’s Bandage Project, an organization raising money for pediatric cancer and collecting fun bandages for children in treatment. Brock challenged another young agent across Kansaswhoever lost had to get a bandage-themed tattoo.
The result was wildly effective: the effort helped collect over one million bandages and raise about $10,000 in roughly a month. Then they delivered the bandages to kidswho, as you might guess, were delighted to see the tattoo payoff in person. Cute bandages, real support, and a story that travels farther than a standard donation ask.
What independent agencies can learn from this (without getting inked)
- Gamify the mission: Friendly competition drives urgency without turning the cause into a sales pitch.
- Make the impact visible: Delivering the bandages isn’t just logistics; it’s meaning.
- Let your community do the heavy lifting: Brock’s point is consistentpeople together scale impact.
- Build brand the right way: Community service becomes credibility when it’s consistent and sincere.
Advocacy: The Unsexy Superpower of Independent Agents
Brock also leans into an aspect of insurance that most civilians never see: government affairs. He’s been active in Kansas association work and has served as chair of a state government affairs committee. He’s candid about disliking the “political” part, but he cares about the machinerystatutes, bill writing, and behind-the-scenes decisions that affect agencies and clients.
InsurPac, explained like you’re not trapped at a conference booth
In the Big “I” ecosystem, InsurPac is the federal political action committee associated with independent agents, and it exists to help the independent agency channel keep a “seat at the table.” The basics: industry participants contribute, and InsurPac supports federal candidates who back small business and the independent agent system. State associations often pair that with state-level PAC efforts, too.
If that sounds distant from day-to-day agency work, it isn’t. Insurance is regulated primarily at the state level, and state rules vary. When laws shifton everything from insurance regulation frameworks to specific commercial-line mechanicsagencies and clients feel it. Advocacy is how independent agents protect their ability to operate and serve customers effectively.
The Future of the Industry: “We Can’t Just Be Insurance Agents Anymore”
Brock works primarily with mid-market commercial clients, and his message is blunt: agents can’t act like they’re just selling policies. The modern independent agent is expected to be a solutions partner.
That doesn’t mean pretending you’re a lawyer, an HR consultant, and a cybersecurity engineer in one. It means building a practical support system around your clients’ risks:
- Risk discovery: asking the questions that uncover exposures before a claim does.
- Coverage strategy: aligning limits, deductibles, and endorsements to real operations.
- Claims guidance: helping clients navigate the process when stress is high and time is short.
- Prevention mindset: encouraging safer practices that reduce losses and stabilize costs.
- Carrier navigation: knowing which markets fit which risksand when to pivot.
This approach lines up with what consumers expect from independent agents: the ability to shop among multiple carriers, compare coverage, and assist with claims and policy updates. It also aligns with reality: commercial insurance buying often runs through independent agents and brokers because the risk landscape is specialized, messy, and rarely one-size-fits-all.
When Insurance Gets Personal: Brock’s “Why”
Brock’s most serious insight isn’t a sales tipit’s a moment that reminds you why this industry exists. He described a tragic loss involving people he knew, tied to a claim situation where the coverage mattered. A week later, he was able to call the business owner and explain that benefits would pay out and bills wouldn’t add financial chaos to grief.
This is the part of insurance that never makes it into a meme: the work can be quietly life-altering. It’s also a clue for the industry’s recruiting problem. If you only describe insurance as paperwork, you’ll attract people who tolerate paperwork. If you describe it as risk intelligence + human help, you’ll attract people who want to matter.
The Bigger Backdrop: What Independent Agencies Are Up Against
1) Talent shortages are realand measurable
The U.S. Bureau of Labor Statistics projects steady demand for insurance sales agents, with tens of thousands of openings each year, much of it driven by retirements and workforce exits. Meanwhile, industry research and commentary keep returning to the same theme: the pipeline is strained, and frontline roles (claims, agents, service) are critical entry points that need stronger development paths.
2) Training and mentorship can’t be “nice-to-have”
Workforce commentary around claims and service roles highlights what happens when structured development disappears: burnout rises, mid-career retention weakens, and the industry struggles to replace expertise. Independent agencies that build real training programsshadowing, role rotation, mentorshipdon’t just help new hires; they protect their future revenue.
3) AI is changing workflows, not eliminating relationships
AI and automation are reshaping insurance operationsfrom underwriting to claims to customer engagement. The healthiest agencies aren’t using tech to “replace humans,” but to remove low-value friction: fewer manual tasks, faster turnaround, better data capture, and more time for advisory conversations. If Brock’s “solutions outside the policy” point is the destination, modern tech is part of the transportation.
4) Regulation is complicatedadvocacy keeps it navigable
U.S. insurance regulation is primarily state-based, rooted in historical policy choices and reinforced over decades. That structure affects licensing, market conduct oversight, solvency standards, and more. It’s also why agency advocacy groups exist: the rules are real, and someone has to show up when the rules are being written.
Practical Takeaways You Can Steal (Ethically) From Brock Elliott’s Playbook
If you’re a young agent
- Get involved early: Walk into the room even if you don’t know anyone. Someone will talk to you.
- Try roles, then choose: Sales isn’t the only path. Account management and service build real mastery.
- Find your “why”: Compensation and flexibility are great, but purpose makes careers durable.
- Build a community habit: Service projects can turn networking into lifelong relationships.
If you run an agency
- Stop “telephone-book onboarding”: Create structured development. It pays for itself.
- Make succession a project, not a crisis: Brock’s five-year goalmaking work optional for his dadis smart planning.
- Modernize your value proposition: Teach producers to lead risk conversations, not just quote conversations.
- Support advocacy: Policy changes can hit your clients’ bottom line and your agency’s ability to compete.
If you’re a business owner shopping for coverage
- Ask for options: Independent agents can compare across carriersuse that advantage.
- Ask about risk, not just price: The best agencies help you spot exposures before they become losses.
- Ask what happens in a claim: The difference between “policy purchased” and “problem solved” shows up here.
FAQ: Declaration of Independents, Brock Elliott, and the Independent Channel
Is “Declaration of Independents” a political series?
Nope. It’s a leadership-and-identity series highlighting independent insurance professionalsthough it does include advocacy, because regulation and legislation affect the industry every day.
What’s the Big “I”?
“Big I” refers to the Independent Insurance Agents & Brokers of America (IIABA) and its network of state associations, programs, and advocacy efforts that support the independent agency system.
Why do young agent committees matter?
They build leadership pipelines, develop talent, create peer networks, and often drive community service and political involvement all of which help keep the independent channel healthy.
What makes an independent agent different from a captive agent?
Independent agents can work with multiple carriers rather than being tied to a single company. That typically means more choice, more flexibility, and a stronger ability to match coverage to real-world needs.
Conclusion
The headline of Brock Elliott’s IA Magazine feature could’ve been “young leader wins award,” and that would’ve been truebut boring. The real story is more useful: independence isn’t just about carrier choice. It’s about community leverage, advocacy muscle, and evolving from policy placement into problem-solving.
Brock’s career shows what happens when an agency professional stops trying to force-fit a role and starts building a career around relationships, purpose, and leadership. He modernized a young agents program, turned philanthropy into real impact (and a tattoo), and treats advocacy as part of protecting clients and the independent channel. That’s a declaration worth readingand borrowing from.
Experience Appendix: 10 Real-World Experiences Inspired by Brock Elliott’s Story (500+ Words)
1) The “wrong seat” season. Many new agency hires discover early that “sales” is a big word with a lot of different jobs hiding inside it. Some people love cold outreach; others are built for account management, renewals, coverage reviews, or claims guidance. A common experience is feeling like you’re failinguntil you realize you’re just miscast. Switching roles can turn “I’m not good at this” into “oh, this is what my brain likes.”
2) The first claim that changes you. Agents often remember the first serious claim where the outcome truly matters: a business interruption situation, a serious injury, a devastating property loss. People in the independent channel regularly describe the same emotional pivotinsurance stops being a product and becomes a promise. That moment is frequently what creates long-term commitment to the work.
3) Walking into the room where you know nobody. Young agent events and association meetings can feel like the first day of school. A typical experience is showing up awkwardly, hovering near the coffee, and then discovering that insurance people aresurprisinglyvery friendly. The industry is relationship-driven, so most communities reward the courage to show up.
4) Service projects that actually build business (the right way). When agencies participate in community campaigns, they often notice two outcomes at once: real local impact and stronger trust. Not “marketing” trustthe kind where community partners remember you when decisions are being made. A fundraiser with a clear mission, a measurable goal, and visible results frequently creates relationships that last far beyond a single event.
5) The power of a friendly competition. People love a scoreboard. In many communities, a small challengebetween teams, offices, or chapters drives engagement that a generic donation link never will. The experience is consistent: once you add a playful constraint (time limit, goal meter, harmless penalty), participation rises because it’s fun and meaningful at the same time.
6) “I didn’t care about politics… until I saw the bill.” Plenty of agents don’t start out interested in legislation. The shift often happens when a proposal clearly affects clients, premiums, coverage availability, or business operations. People commonly describe a second pivot here: advocacy becomes practical, not ideologicalmore about protecting the ability to serve customers effectively.
7) Becoming a solutions partner is messy at first. Agencies transitioning from quote-centric workflows to risk-advisory conversations often experience a short, uncomfortable learning curve. You have to ask better questions, document exposures, coordinate with carriers, and sometimes deliver hard truths. Over time, clients tend to respond wellbecause most business owners don’t want “a policy,” they want fewer surprises.
8) Tech that gives time back (when implemented sanely). Many teams report the same experience with automation: if you digitize chaos, you get faster chaos. But when you use tools to streamline the right stepsdata capture, renewal reminders, submission quality you buy time for higher-value work like coverage strategy and client education. The best implementations feel like breathing room.
9) Succession planning is emotional, not just financial. In family agencies especially, perpetuation planning can be deeply personal. People describe navigating identity (“Who am I if I’m not working?”), fairness (“What about siblings?”), and timing (“How fast is too fast?”). A five-year horizon often helps because it creates structure without forcing a cliff jump.
10) Finding your “why” is often a slow reveal. Not everyone starts with a grand purpose. Many professionals describe discovering meaning through repetition: helping a client after a loss, coaching a new hire, building a community initiative, or advocating for something that improves the industry. Eventually the “why” becomes obviousbecause you’re living it.